Is Buying a House at 5-7% Interest Rate Worth It in 2026? (The Math Says Yes—But Not Always)
I’ve spent the last eighteen months watching clients paralyze themselves waiting for mortgage rates to drop below 4%. They check rate forecasts like slot machine pulls. They delay offers. They miss properties. Then rates stayed put—or climbed higher. Most of them would be $80,000 to $120,000 wealthier today if they had bought at 5.5% instead of waiting.
The emotional pull of “rates will drop” is powerful. But emotion is not math. Here are the actual numbers.
Why 5-7% Feels Catastrophic (But Is Not Always)
Your brain remembers 2021. Rates were 2.96% that January. A $400,000 mortgage meant a $1,686 monthly payment. At 5.5% today, that same loan costs $2,271 per month—$585 more, 35% higher. No wonder people freeze.
But homes cost $50,000 to $120,000 more than they did in 2021. Rates did not go up in a vacuum. The real question is not “how bad is 5.5%?” It is “what will this house cost in 24 months if I wait?”
The $87,000 Price of Waiting (Real Numbers)
Assume modest 4% annual appreciation. A home you buy for $500,000 today costs $520,000 in 24 months.
Option A: Buy now at 5.5%
Monthly payment: $2,839. Down payment: $100,000. You start building equity immediately.
Option B: Wait 24 months, rates drop to 4.2%
New price: $520,000. Monthly payment: $2,448. You save $391 per month—but you paid $20,000 more for the home, paid $52,800 in rent over 24 months, and face closing costs again. Net real-wealth position: down $14,040. And that assumes rates actually drop. If they do not, you are down $72,800.
The Break-Even Calculation (When Waiting Makes Sense)
Waiting only wins if two things happen simultaneously: home prices stagnate or decline 8%+ AND rates drop below 4%. In the last 50 years, that combination occurred roughly 12% of the time. You are betting on a 1-in-8 scenario while paying rent and missing appreciation.
The break-even window is 18-22 months. After that, you have already lost ground regardless of what rates do. If you are waiting for rates below 3.8%, you are statistically waiting for a 2008-style recession.
The Refinance Exit Ramp
Buying at 5.5% is not a lifetime sentence. If rates drop to 4.2% within 36 months, you refinance. Closing costs run $4,000 to $6,000. You break even in 15 months. After that, pure savings. In the last 20 years, the average homebuyer who refinanced at least once saved $74,000 over the life of their mortgage.
The psychological trap: people treat a rate lock like a permanent condition. It is not. It is a position you can exit when rates move meaningfully lower.
When Waiting Is Actually Right (The Honest Answer)
You are in a genuinely declining market. Cities losing population and jobs with prices down 5-8% year over year—wait. Buy the bottom. This is rare.
The payment breaks your budget. If $2,271 monthly is unmanageable and rent is $1,900, do not stretch. But then you are not waiting for rates—you are saving for a larger down payment.
You need 12-18 months to prepare anyway. Timing an 18-month window is easier than timing a decade.
If you are waiting because “rates will obviously drop soon”—that is emotion, not strategy. Markets do not wait for your comfort.
Action step: Run your actual break-even calculation. Assume 3-5% annual appreciation in your market. Assume rates stay flat. Ask yourself honestly: do I believe home prices will fall while I wait? If the answer is no, the math already made the decision for you.
Renting vs. Buying at 6%: The True Cost of Waiting
Rate-waiters typically ignore what renting costs during the wait. Paying $2,200/month in rent for 18 months while rates drop from 6.5% to 5.5% means $39,600 in rent paid — none of which builds equity. Meanwhile, home prices in most markets appreciate 3–5% annually, adding $15,000–$25,000 to the cost of the home you’re waiting to buy.
How DTI Changes at Different Rate Levels
At 7%, a $400,000 mortgage costs $2,661/month. At 5.5%, the same loan costs $2,271 — a $390 difference. This swing affects DTI qualification: at 7% you need ~$8,200/month gross income; at 5.5% you need ~$7,100. The real case for waiting is not the monthly payment but the loan size you qualify for.
Buy Now or Wait: A Decision Framework
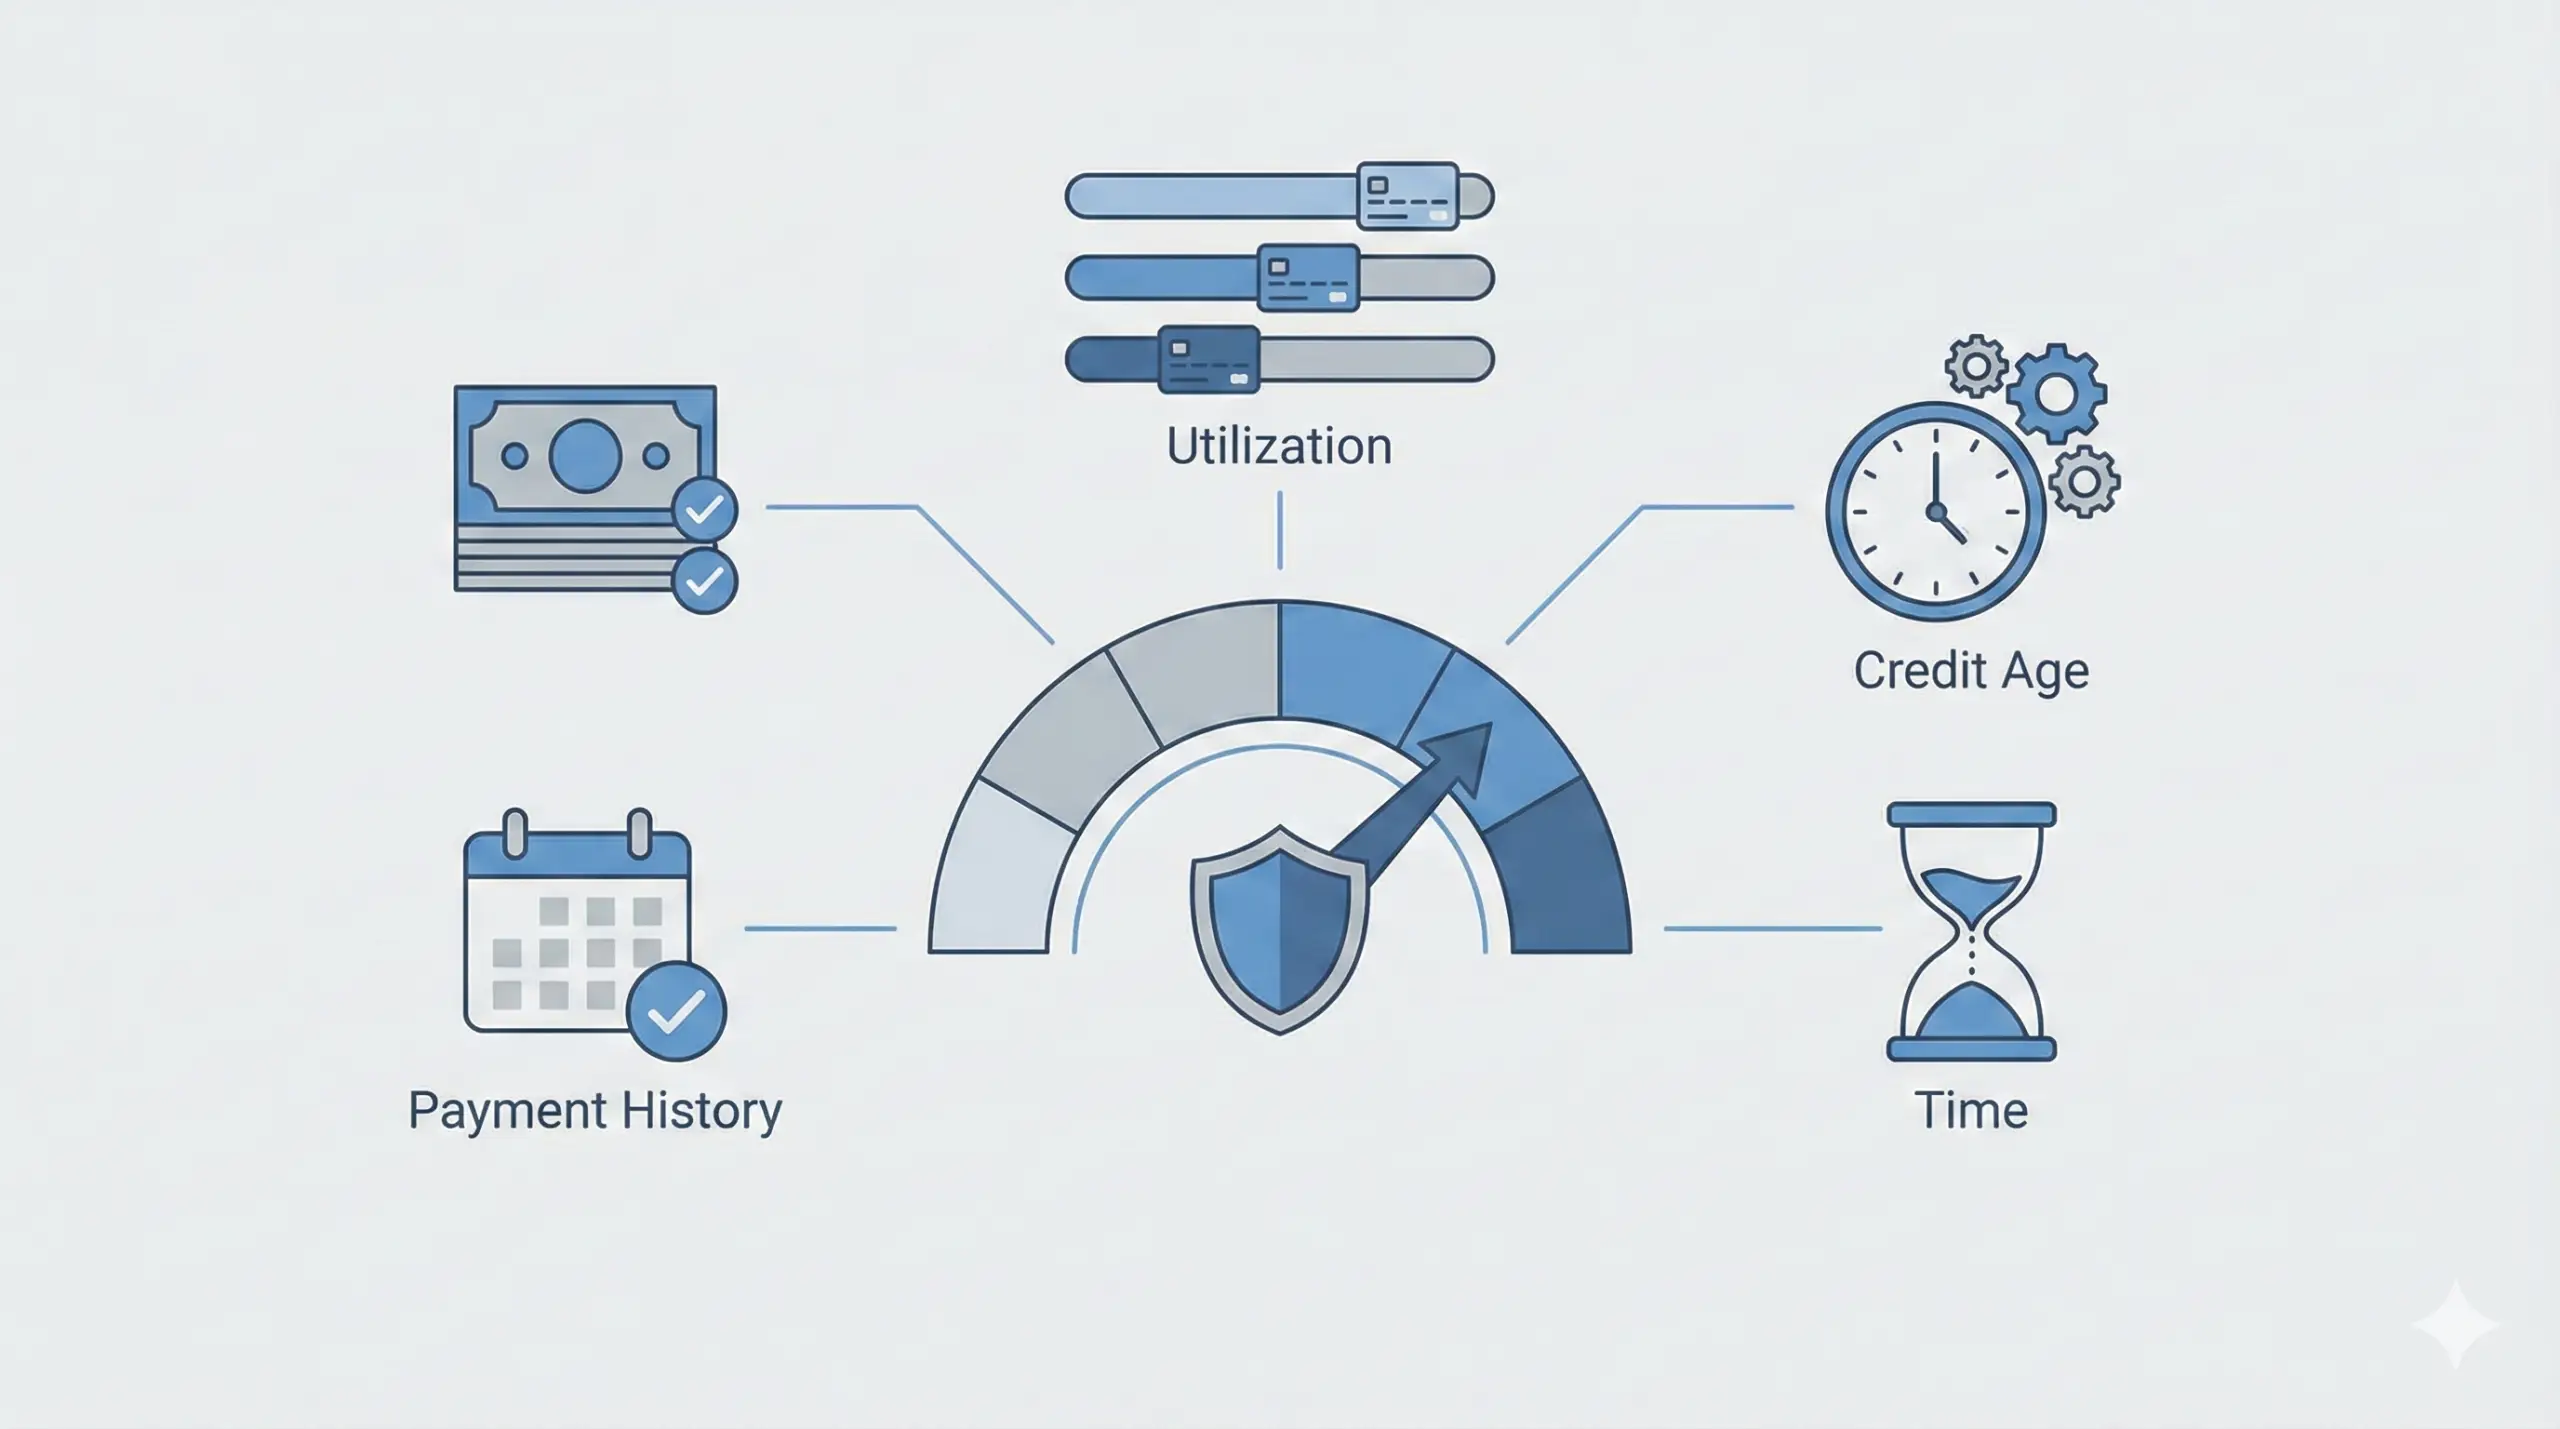
- Buy now if: You plan to stay 7+ years, rents are near equivalent mortgage payments, and your financial position is strong (760+ credit, stable income, 6-month reserves)
- Wait if: You’ll likely move within 3 years, your market shows clear price softening, or you need 6–12 months to improve credit or save more down payment
The refinance option is your safety valve: buy at today’s rate with a plan to refinance when rates drop below your trigger point (typically 0.75–1% lower with 2–3 year break-even on closing costs).
.lwrp.link-whisper-related-posts{margin-top: 40px; margin-bottom: 30px; } .lwrp .lwrp-title{
}.lwrp .lwrp-description{
} .lwrp .lwrp-list-container{ } .lwrp .lwrp-list-multi-container{ display: flex; } .lwrp .lwrp-list-double{ width: 48%; } .lwrp .lwrp-list-triple{ width: 32%; } .lwrp .lwrp-list-row-container{ display: flex; justify-content: space-between; } .lwrp .lwrp-list-row-container .lwrp-list-item{ width: calc(25% – 20px); } .lwrp .lwrp-list-item:not(.lwrp-no-posts-message-item){
max-width: 150px; } .lwrp .lwrp-list-item img{ max-width: 100%; height: auto; object-fit: cover; aspect-ratio: 1 / 1; } .lwrp .lwrp-list-item.lwrp-empty-list-item{ background: initial !important; } .lwrp .lwrp-list-item .lwrp-list-link .lwrp-list-link-title-text, .lwrp .lwrp-list-item .lwrp-list-no-posts-message{
}@media screen and (max-width: 480px) { .lwrp.link-whisper-related-posts{
} .lwrp .lwrp-title{
}.lwrp .lwrp-description{
} .lwrp .lwrp-list-multi-container{ flex-direction: column; } .lwrp .lwrp-list-multi-container ul.lwrp-list{ margin-top: 0px; margin-bottom: 0px; padding-top: 0px; padding-bottom: 0px; } .lwrp .lwrp-list-double, .lwrp .lwrp-list-triple{ width: 100%; } .lwrp .lwrp-list-row-container{ justify-content: initial; flex-direction: column; } .lwrp .lwrp-list-row-container .lwrp-list-item{ width: 100%; } .lwrp .lwrp-list-item:not(.lwrp-no-posts-message-item){
max-width: initial; } .lwrp .lwrp-list-item .lwrp-list-link .lwrp-list-link-title-text, .lwrp .lwrp-list-item .lwrp-list-no-posts-message{
}; }
Related Posts
Renting vs. Buying at 6%: The True Cost of Waiting
Rate-waiters typically ignore what renting costs while they wait. If you’re paying $2,200/month in rent and waiting 18 months for rates to drop from 6.5% to 5.5%, that’s $39,600 in rent — none of which builds equity. Meanwhile, home prices in most markets appreciate 3–5% annually, adding $15,000–$25,000 to the cost of the home you plan to buy. The math rarely favors waiting more than 12 months, even when rates do fall modestly.
How DTI Changes at Different Rate Levels
At 7%, a $400,000 mortgage costs $2,661/month in principal and interest. At 5.5%, that same loan costs $2,271 — a $390 difference. That swing affects your debt-to-income ratio and determines loan eligibility. To qualify for $400k at 43% DTI: at 7% you need ~$8,200/month gross income; at 5.5% you need ~$7,100. This is the real case for waiting — not the payment amount, but the loan size you can qualify for.
Decision Framework: Buy Now or Wait
- Buy now if: You plan to stay 7+ years, rents in your market are near equivalent mortgage payments, and your financial position is strong (760+ credit, stable income, 6-month reserves)
- Wait if: You’ll likely move within 3 years, your market shows clear price softening, or you need 6–12 months to strengthen your credit or save more down payment
The refinance option is your safety valve: buy at today’s rate with a plan to refinance when rates drop. Most advisors suggest refinancing makes sense when you can reduce your rate by 0.75–1%+ and plan to stay long enough to recoup closing costs (typically 2–3 years).